This page describes the situation in the Netherlands. Glass damage that the insured person causes themselves is often covered as standard by the buildings insurance or home contents insurance. Sometimes an extra module can be added to the insurance for this. If the damage is caused by someone else, the personal liability insurance (AVP) of the liable party will, for example, pay for the damage. However, even if the damage is caused by someone else, the insured person can still turn to their own buildings or home contents insurance. The insurer will then recover the damage from the liable party or from the liable party's insurer. This is called recourse (regres).
Glass damage and liability
Whoever breaks the glass has to pay for it. Or at least, they do if they made a mistake for which they can be blamed. This means that if a painter drops a ladder and breaks glass, the painter has to pay for that damage. If the neighbours' children are playing with a ball and cause glass damage at someone else's home, the parents of these children will have to pay for the damage. Also, when a roof tile flies off the neighbours' roof and causes glass damage elsewhere, the neighbours may be liable for that damage. Most people in the Netherlands have personal liability insurance (AVP). This insurance usually pays for glass damage for which the policyholder is liable.
Personal liability insuranceExcess
Personal liability insurance will not automatically pay for all damage. Not because the amounts covered are limited, as these limits are often 1.25 or €2.5 million. But because an excess often applies. This means that you have to pay part of the damage yourself. If, for example, the glass damage amounts to €1,000 and the excess is €150, the AVP insurer will only pay €850. The remaining €150 still has to be paid by the liable party. There are also AVP policies without an excess.
Children and liability for glass damage
AVP insurance first of all covers fault-based liability. This means that it pays for damage for which the insured person is liable because they made a mistake and caused damage as a result. In other words, the insured person can be blamed for something. Secondly, AVP insurance covers strict liability, the form of liability in which fault or blame plays no role. This is the case, for example, for the liability of parents for their children. This means that if children damage the neighbours' windows, the parents' AVP insurance will pay for it. This applies even if the children act intentionally.
Liability of parents for their children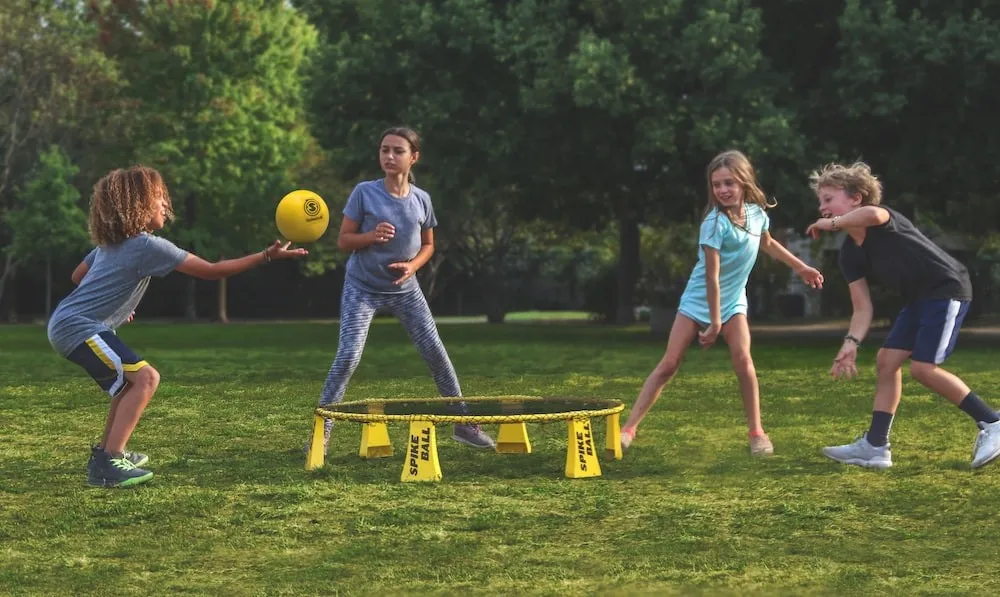
Animals and liability for glass damage
Strict liability is not only about the liability of parents for their children, but also about the liability of animal owners for their animals. Dogs, for example, can also cause glass damage. This usually involves a dog jumping up against the glass and scratching the window with its paws. Most AVP policies also cover liability for damage caused by animals. With some AVP insurers, this can be added to the policy as an option.
Liability of animal owners for their animals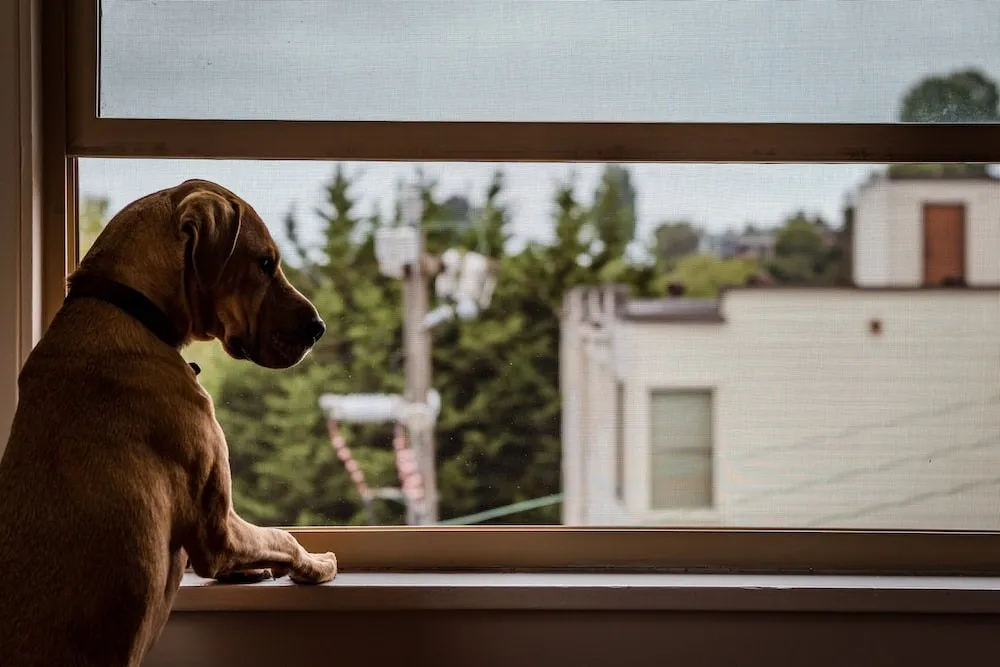
Cost of glass insurance
Someone else will not always be liable for the glass damage. One's own children may have damaged their parents' windows, for example. Or the home's own windows may have been broken during DIY or a house move. For owner-occupied homes, this is covered by buildings insurance. Sometimes this is included as standard, but sometimes it is optional cover. For rented homes, it is covered by home contents insurance, here too either as standard or as an option. Ordinary glass is usually just covered. For other types of glass, a higher excess sometimes applies, or it is not covered at all.
Cost of glass insurance for windows
Ordinary glass is covered by almost all glass insurers. Most insurers do not apply an excess, but some insurers do. This varies from €20 to €250. A number of insurers also use claims steering. This means that there is no excess when a repair company that the insurer works with is used.
Cost of glass insurance for roof windows
Roof windows are extra vulnerable to hail damage, but are less likely to be damaged by, for example, children playing. As a result, the risk for the insurer is comparable to the risk with traditional glass. This means that most insurers do not charge extra for roof windows.
Cost of glass insurance for double glazing
Double glazing (or better) has become the standard nowadays. That is why insurers do not charge extra for insuring double glazing. Bear in mind, though, that restrictions sometimes apply. Some insurers, for example, only cover glass damage if the glass is no more than ten years old.
Cost of glass insurance for leaded glass
Leaded glass is extra expensive. Repair costs can be high. That is why there are buildings insurance policies that do not pay for glass damage to leaded glass. Some insurers do. This can affect the cost of the glass insurance.
Cost of glass insurance for shower cabins
With most insurers, damage to glass shower cabins is covered by the glass insurance as standard. The cost of the glass insurance is not higher as a result. Whether or not glass damage to shower cabins is covered can be found in the policy.
Cost of glass insurance for greenhouses
Greenhouses and hobby greenhouses are extra vulnerable to storm damage. That is why they are not always covered by glass insurance. In fact, only a handful of buildings insurers cover this. This can make the glass insurance of these insurers slightly more expensive.
Cost of glass insurance for domed skylights
The same applies to domed skylights as to roof windows: on the one hand, these skylights are more susceptible to hail damage, for example, but on the other hand, the risk of damage from children playing is more limited. As a result, most insurers insure domed skylights at no extra cost or do not explicitly exclude them in the policy conditions.
Cost of glass insurance for thermal breakage or leakage
Double or triple glazing has one or more extra layers in the glass. This gives it a higher insulation value. Not only are these windows more expensive than single glazing, a leak can also immediately have destructive consequences. Many insurers also cover thermal breakage or leaks, and at no extra cost. Restrictions do sometimes apply. For example, a leak in double glazing is sometimes not insured if the glass is more than ten years old.
Insurers that offer glass cover
There are quite a few insurers that offer glass insurance. Sometimes glass cover is included as standard in the home contents or buildings insurance, and sometimes it can be added as an extra. An optional addition will of course make the buildings or home contents insurance more expensive. Most Dutch insurers offer their website and policy documents in Dutch only.
| Insurer | Name of insurance | Glass cover in buildings insurance | Glass cover in home contents insurance for owners | Glass cover in home contents insurance for tenants/owners' association (VvE) |
|---|---|---|---|---|
| A.s.r. | Woonhuisverzekering | Yes | Optional | Optional |
| ABN Amro | Woonhuisverzekering | Yes | No | Optional |
| ABN Amro | Woonhuisverzekering Basis | Yes | No | No |
| Aegon | Opstal Basis | Optional | No | Optional |
| Aegon | Opstal Allrisk | Yes | No | Yes |
| Allianz | Woonhuisverzekering | Optional | Optional | Optional |
| Allianz Direct | Opstalverzekering | Yes | Optional | Optional |
| ANWB | Opstalverzekering | Yes | Yes | Yes |
| Aon | Woonhuisverzekering | Yes | Optional | Optional |
| Centraal Beheer | Opstalgarant Verzekering | Yes | No | Yes |
| De Goudse | Woonhuisverzekering | Optional | Optional | Optional |
| FBTO | Woonhuisverzekering | Optional | No | Yes |
| ING | Woonhuisverzekering | Yes | Optional | Optional |
| Inshared | Opstalverzekering | Optional | Optional | Optional |
| Interpolis | Woonhuisverzekering | Yes | No | Yes |
| Klaverblad | Woonhuisverzekering | Optional | Optional | Optional |
| Nationale-Nederlanden | Woonhuisverzekering | Optional | Optional | Optional |
| Nationale-Nederlanden | Woonhuisverzekering Maatwerk All-in | Yes | Optional | Optional |
| Ohra | Opstalverzekering (EUG) | Optional | Optional | Optional |
| Ohra | Opstalverzekering (AR) | Yes | Optional | Optional |
| Rhion | Woonhuisverzekering | Yes | No | Optional |
| SNS | Woonhuisverzekering | Yes | Optional | Optional |
| Unigarant | Opstalverzekering | Yes | Yes | Yes |
| United Insurance | Woonhuisverzekering | Yes | Optional | Optional |
| Univé | Opstalverzekering (EUG) | Optional | Optional | Optional |
| Univé | Opstalverzekering (AR) | Yes | Optional | Optional |
| Vereniging Eigen Huis | Woonhuisverzekering | Yes | Optional | Optional |
| Verzekeruzelf.nl | Woonhuisverzekering | Optional | Optional | Optional |
| ZLM | Woonhuisverzekering | Optional | No | Optional |
Comparing glass insurance
There are a number of things to look out for when comparing glass insurance. A comparison of the policy conditions of the largest glass insurers in the Netherlands shows that there are a number of questions to ask.
| Question to ask | Explanation |
|---|---|
| What is the excess for glass damage? | Most insurers do not apply an excess. A number of insurers do. The excess then varies between €20 and €250 per claim. |
| Is leaded glass covered? | Many insurers limit cover to "ordinary glass". |
| Is glass in balconies covered? | With a number of insurers, glass in balconies is excluded. |
| Is decorated or painted glass covered? | Only a limited number of insurers cover damage to decorated or painted glass. |
| Is damage to a (hobby) greenhouse covered? | There are not many insurers that pay for damage to a (hobby) greenhouse. |
| Is there an exclusion for damage during renovation work? | Most insurers exclude glass damage that occurs during a renovation. |
| Is there an exclusion for homes that are left empty for a long time? | Some insurers exclude glass damage when the home has been empty for a number of months. This is out of fear of vandalism and squatters as a result of the vacancy. |
| Is claims steering used? | With a number of insurers, no excess applies provided that the policyholder uses a repair company with which the insurer has an agreement. |
| What is the price of the glass insurance? | With some insurers, glass insurance is included as standard in the buildings or home contents insurance. With other insurers, it has to be added as an option at an extra cost. The amount of that extra cost differs per insurer. |
Because glass insurance is part of buildings insurance and home contents insurance, it is advisable to look at the bigger picture. The other conditions in the buildings or home contents insurance also determine whether or not this insurance is worthwhile.
Compare buildings insuranceCompare home contents insuranceCompare insurers
 8.7
 8.5
 8.5
WA.nl may receive a commission if a policy is taken out via one of these buttons.
Frequently asked questions about taking out glass insurance
There are relatively many differences between glass insurance policies in the Netherlands. For example, there are often exclusions and sometimes an excess applies. This naturally raises questions from time to time. The FAQ about glass insurance below answers the main questions.
How and where can glass insurance be taken out?
Glass insurance is sometimes part of home contents insurance or buildings insurance. In that case, it is not necessary to take out additional glass insurance. With some insurers, it can be added to the home contents or buildings insurance as an option. Contact the insurer and check whether glass damage is sufficiently covered by the insurance.
What are the extra costs of glass cover?
With some insurers, glass cover is included as standard, while other insurers offer it as a paid module. The exact price depends on various factors and differs per insurer; the extra cost comes on top of the premium for the home contents or buildings insurance.
Does glass insurance also cover leaks in double glazing?
Yes, with most insurers a leak or break in double glazing is also simply insured. Bear in mind, however, that there are sometimes exclusions and restrictions. For example, the glass may not be more than ten years old, or damage during renovation work is excluded. This differs per insurer.
Is extra glass insurance needed when renting a home?
This depends on the specific situation. Some landlords have already taken out glass insurance, in which case it is not necessary to take out extra glass insurance yourself. If the landlord has not taken out glass insurance, it is advisable to do so yourself. Sometimes the tenancy agreement states whether or not the landlord has glass insurance. If in doubt, contact the landlord.
Is thermal glass breakage insured?
The conditions differ per insurer. Thermal glass breakage is often covered, but restrictions apply. For example, the windows may not be more than ten years old. So always read the policy conditions carefully and avoid unpleasant surprises.
Is glass damage covered by buildings or home contents insurance?
For owner-occupied homes, glass damage is covered by buildings insurance, either as standard or as an option. For rented homes, it is covered by home contents insurance, here too either as standard or as an option. Exactly what glass cover a policy includes is set out in the policy conditions.